
Twelve Ways Plot Buyers Lose Money in Telangana
Fraud is rare. Carelessness is not, and it costs the same. Almost every plot-buying loss around Hyderabad comes from one of twelve ordinary errors — a certificate not pulled, a price that looked generous, a layout that was about to be approved. Each is listed below with the specific habit that prevents it. If a plot you are considering trips even one, stop and resolve it before money moves.
Land forgives very little. An apartment with a defect can usually be repaired or litigated within a building that exists. A plot with a defect can be a decade of proceedings over an asset you cannot use, cannot sell and cannot borrow against.
The encouraging part is the concentration. The same dozen errors account for the overwhelming share of the damage, and every one is avoidable with checks measured in days.
1. Buying unapproved because it is cheaper
The most common error and the most damaging. Unapproved subdivisions — gram-panchayat-era layouts, farm plots dressed as house plots — trade at a discount precisely because they lack HMDA or DTCP sanction. The discount is the market pricing the consequences: no assured roads or open spaces, obstacles at building permission, difficult resale, and dependence on a regularisation scheme that is discretionary and fee-bearing.
The habit: treat the layout permission number as the entry ticket. Verify it with the authority itself, and confirm your plot number sits on the sanctioned plan outside open-space and mortgaged blocks. It is the first gate in our investment checklist, and it is first for a reason.
2. Skipping the Encumbrance Certificate
Buyers accept a seller's word, or a single sale deed, as proof of a clean history. The EC from the Registration & Stamps Department exists so that you need not. It lists registered transactions, mortgages and releases against the property. Not pulling it, or pulling only recent years, is how buyers inherit undischarged mortgages and meet rival deeds.
The habit: obtain the EC for the maximum period yourself, online or at a MeeSeva centre, and reconcile every entry against the seller's account of the chain.
3. Trusting a deed without its links
A registered deed in the seller's name feels conclusive. It proves one transaction, not good title. Missing heirs, unregistered intermediate transfers and defective partitions all hide in the links.
The habit: insist on roughly thirty years of link documents and have a property advocate read them as a chain rather than as a stack. Our legal verification guide shows how that reading works.
4. Entering a GPA transaction
General-power-of-attorney "sales" persist because they look cheaper and faster. They convey no title — the Supreme Court said so plainly in 2011 — they can be revoked, and they collapse on the principal's death. What you pay in such a deal buys a dispute, not a plot.
The habit: registered sale deed, executed by the recorded owner or a lawfully authorised representative whose authority you have examined. No exceptions, at any discount.
5. Ignoring the land's agricultural past
Plots carved from farmland without NALA conversion, or from restricted categories such as assigned or endowment land, carry defects no brochure cures. The failure is invisible at site level. The plot looks exactly like every other plot.
The habit: check the revenue record — Dharani, pahani, 1B — for classification and continuity, and ask for conversion proceedings covering the layout's survey numbers specifically.
6. Deciding on price alone
A plot is not a commodity where the cheapest identical unit wins. Two plots at similar prices can differ completely in approval status, infrastructure, title quality and corridor prospects. Chasing the lowest per-square-yard figure reliably selects for the weakest bundle of those attributes.
The habit: compare total propositions — legal standing, infrastructure actually built, community quality, location trajectory — and read an outlier low price as information rather than luck.
7. Where buyers get hurt: cash into a hand that is not the seller's
This one deserves more than a line, because the money is gone the moment it changes hands.
A buyer is told the plot is moving and a token will hold it. The person asking is an intermediary — a broker, a "channel partner", someone introduced by a friend. The amount is modest by the standards of the transaction, so it is paid in cash, or transferred to the intermediary's personal account, against a handwritten note or nothing at all.
Then something falls through. The title opinion is adverse, or the plot was already committed, or the intermediary was never authorised to receive money on the seller's behalf. The buyer asks for the token back and finds there is no document connecting that payment to the seller at all. The seller says they never received it. The intermediary stops answering. There is no receipt, no bank trail to a named party, and no agreement referencing the amount — so there is nothing to sue on except the intermediary personally, which is rarely worth what it costs.
Demand three things and this failure cannot occur. Pay only into the seller's own named bank account, never an individual's account and never in cash. Take a numbered receipt on the seller's letterhead that names the plot, the amount and the agreement or booking reference it belongs to. And where an intermediary is involved, ask to see the written authority under which they act for the seller. A genuine agent produces it without discomfort. Someone who cannot has just explained why the money was going to their account.
8. Not standing on the land
Remote purchases, common among NRI buyers, sometimes complete without anyone from the family walking the plot. Photographs do not reveal a low-lying corner, a nala at the boundary, a transmission line overhead, or what the approach road becomes after rain.
The habit: visit before committing, and inspect beyond the plot — the kilometre around it shapes daily life and resale. A structured site visit with your own questions beats a guided tour. Where travel is genuinely impossible, send a trusted representative and commission an independent surveyor's report.
9. Not reading the master plan
Buyers examine the layout and ignore the canvas it sits on. Land-use zoning, road proposals and buffer rules around water bodies decide what surrounds you in ten years, and whether a proposed alignment passes rather closer than you would like.
The habit: check the land-use map for the layout's zone and its surroundings, and ask specifically about proposed alignments — a live question near the Regional Ring Road. Distinguish proposed from sanctioned from built; each deserves a different weight in your investment reasoning.
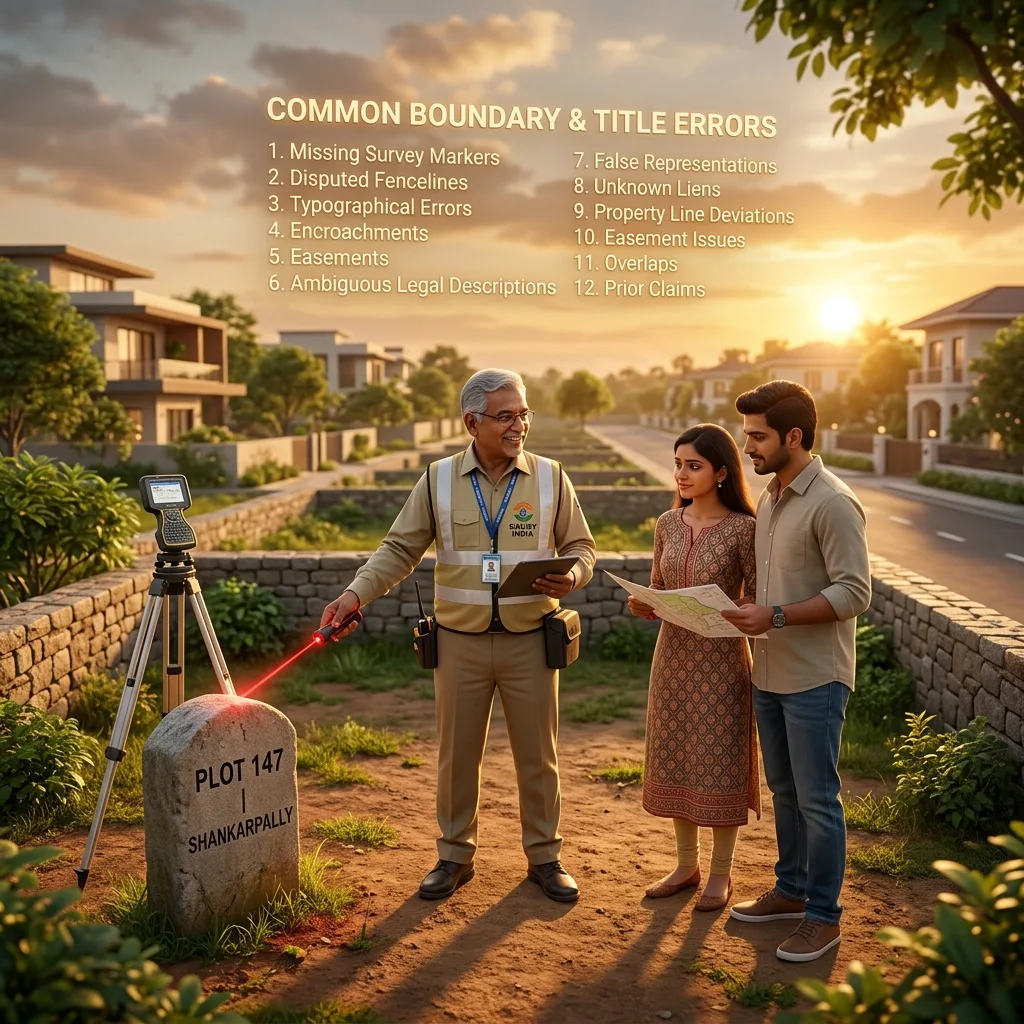
10. Skipping measurement
Deeds occasionally promise more square yards than the ground delivers, and boundaries drift where markers are informal. Discovering a shortfall after registration converts a surveyor's fee you saved into a dispute you fund.
The habit: match boundary markers against the deed schedule and the sanctioned plan, and where anything is unclear, pay a licensed surveyor before you pay the seller.
11. Underestimating the cost of ownership
The plot price is not the project price. Stamp duty and registration fees at rates notified by the Registration & Stamps Department, development charges and corner-plot surcharges, maintenance and corpus contributions in gated communities, annual property tax, and eventually construction and its permissions all belong in the arithmetic. Buyers who ignore them either over-leverage or stall halfway.
The habit: build a total-cost sheet before negotiating, and read our guides on taxation and construction planning so the later chapters are budgeted from day one.
12. Buying with no holding plan
Plots are patient assets. Buyers who arrive expecting apartment-style rental yield or a quick turn exit disappointed, usually at the wrong moment. West Hyderabad's corridor story — the ORR, the Financial District's employment mass, the proposed RRR — compounds over years, not quarters.
The habit: decide your purpose (build, hold, or estate planning), set a horizon in years, budget the carry, and choose the location for reasons that survive a market cycle — the way corridors such as Shankarpally are chosen for schools, rail, ORR access and employment gravity.
Compress it into one week
Run the checks in parallel and the whole syllabus fits into five working days.
Days one and two: paper you can pull yourself — the EC for the maximum period, the layout permission details from HMDA or DTCP, the project's TS-RERA page, the land's Dharani entries. Day three: your advocate receives the deed, the link documents and your gleanings, and returns a list of gaps. Day four: the ground — walk the plot and its kilometre radius, check markers against the plan, drive the approach at peak hour, and put your questions to the developer's face. Day five: arithmetic — the total-cost sheet, the payment schedule tied to documentation milestones, and a night's sleep before anything is signed.
Two things make the sprint work. Sequence: paper before ground, ground before money. And the willingness to stop the clock — if the gap list or the site walk surfaces something unresolved, the week pauses until it is resolved, however warm the negotiation has become. Sellers with clean projects do not fear a paused week. Sellers who push against it are telling you something.
Run this on any plot, including ours. A developer whose answer to scrutiny is more documents rather than more persuasion has passed the most important test a buyer can set. At Sanctuary and Raghunath County, the paperwork is kept to be examined.
This guide is general information, not legal advice. Verification of title and approvals is the buyer's responsibility, professional scrutiny is worth its fee, and real-estate investments are subject to market conditions.