
Saving for a Plot in the Order You Actually Pay
A plot is paid for in four movements, on four different dates, and only one of them is the price. Save against the sequence rather than the sticker figure.
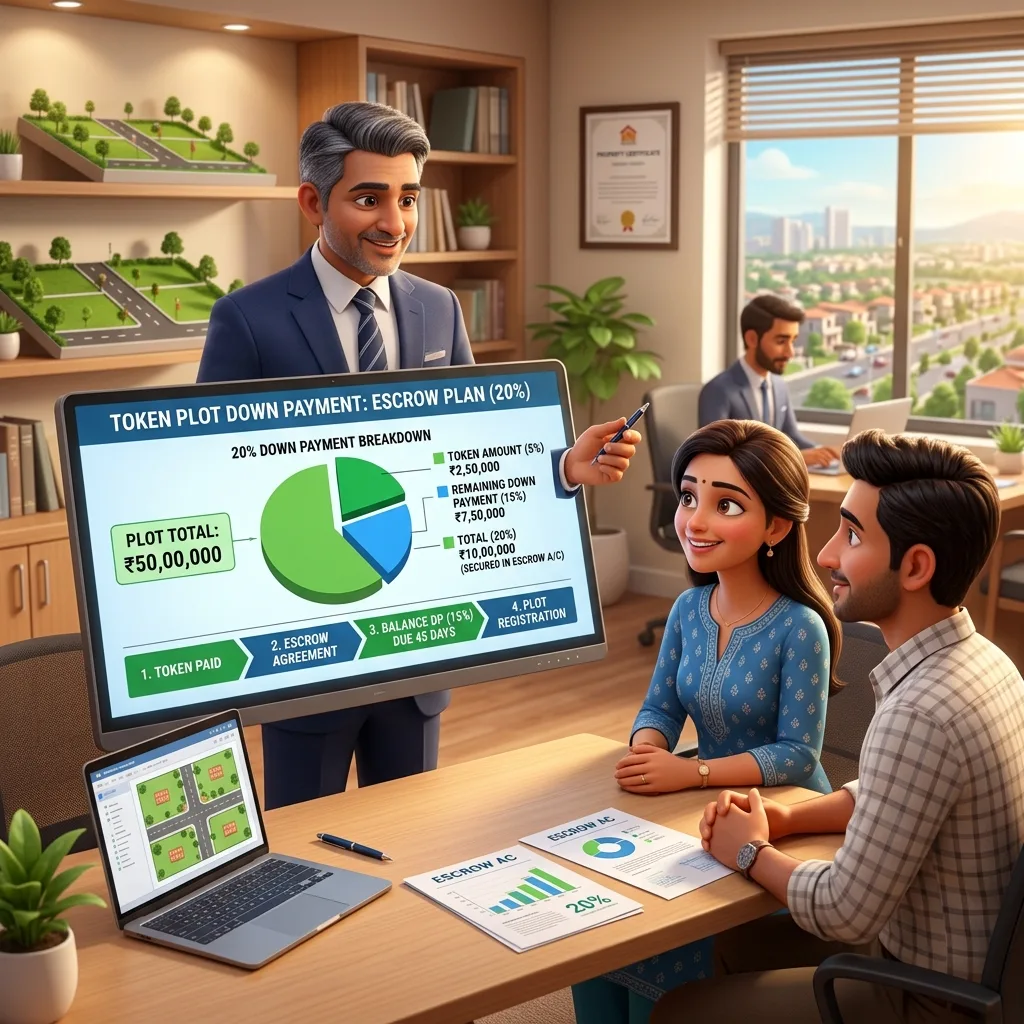
Money leaves a plot buyer's hands in four movements, and they are neither the same size nor due on the same day. A booking or token amount goes first, to hold the plot while terms are settled. A larger tranche follows at the agreement of sale, the written contract recording the price, the parcel and the schedule. Stamp duty and registration charges come third, at the sub-registrar's counter, paid before the deed is registered rather than after. The balance of the consideration lands on or around registration day.
Save against that sequence, not against the price. The price is one obligation. The purchase is four, each with its own date and its own tolerance for delay. Buyers who accumulate a single lump and never ask when each part falls due are the ones improvising in the week before registration.
Work out the whole bill before you save the first rupee
The number your plan must deliver is the acquisition cost. The consideration is only its largest component. Add to it the following, in writing, before you set a monthly target.
- 01Stamp duty and registration charges, at the rates in force in Telangana on the day you register. Do not carry a figure from a friend's purchase two years ago. Check IGRS Telangana, or ask the sub-registrar's office that serves the village your plot sits in.
- 02Legal fees — your own advocate's title search, the encumbrance searches, certified copies. Your advocate, not the seller's.
- 03Project charges — in a gated layout, development or corpus contributions, maintenance deposits, club membership. Ask for the schedule in writing. A number spoken across a desk is not a number.
- 04A buffer you intend never to spend.
Anchor the exercise against something real. Plots at Sanctuary, the HMDA-approved community at Julkal in Shankarpally, start from ₹45 lakh across sizes from 200 to 750 square yards. That figure is the first line of your bill. It is not the bill.
The part nobody will lend you
Lenders treat bare land differently from a built house. They fund a smaller share of a plot's cost, usually over a shorter tenure, and they price the risk differently. Ask your own lender for two things before you build any plan around borrowing: the share of value they will actually fund on a plot in that specific location, and the rate. Both vary by lender, by borrower and by parcel. Anyone quoting a universal figure is guessing on your behalf.
Whatever the lender does not fund is yours, in cash, on the day. So are the transaction costs. Stamp duty, registration charges and your advocate's fee come out of your own account at the counter — no lender disburses them for you, and a sanction letter is not money. This is the structural reason a plot purchase leans harder on savings than a flat purchase does. Our comparison of plot loans and home loans sets out the mechanics.
There is a second concession worth making early. A loan against bare land carries none of the tax relief a self-occupied house attracts, and the treatment of interest during a construction period is a question for a chartered accountant looking at your specific returns, not for a website. Ask one before you decide how much to borrow. The answer changes the arithmetic.
Four accounts, because one account lies
A single balance flatters you. Split the target four ways and watch each separately.
The core corpus is the equity going into the plot itself. It is the largest and slowest bucket, and it is the one most buyers mean when they say they are saving.
The transaction bucket holds duty, registration, legal fees and project charges. Every figure in it is knowable in advance if you ask the right office. It exists as a separate bucket because it is the one that quietly gets spent.
The buffer is a deliberate overshoot. If it survives registration, it becomes your compound wall or your first year of maintenance.
The fourth is your household emergency fund, listed here only to be fenced off. It is not part of this purchase. A plan that closes only by consuming it has not closed.
The point of the split is not tidiness. A buyer who is "eighty per cent there" is usually a buyer whose core corpus is healthy and whose transaction bucket does not exist at all. Four balances show that in month eight rather than month twenty-three.
The first quarter is plumbing, not heroics
Audit three ordinary months of cash flow and establish what you can divert without borrowing from essentials. Open a separate account. Automate a standing transfer on salary day, because a transfer that requires a monthly decision eventually loses an argument. If two of you are saving, automate both sides and agree the split in writing.
Fix the intention on one page at the same time: which corridor, what size range, roughly when. That page is the same purchase thesis we recommend before any negotiation, and for the same reason — it keeps two years of saving pointed at one decision. Our guide to negotiating a plot purchase explains what a written thesis does to your position across a table.
The long middle is supposed to be boring
Money with a date attached is not investment money. For a purchase inside a couple of years, capital preservation and predictable liquidity matter more than yield, which points most savers towards deposits and conservative debt rather than equity. Equity's short-term swings are indifferent to your registration date. Choose specific instruments with a licensed adviser; the principle is what travels.
Handle windfalls by rule rather than by mood. Decide the share of any bonus, incentive or asset sale that goes to the buckets before the money exists. Savers who fix the split in advance capture windfalls. Savers who decide in the moment mostly do not.
A year out, stop saving and start aiming
Shortlist corridors, walk layouts and go on visits while you still have no urgency. This is the cheapest education the market offers, and our site visit checklist exists to stop the visits becoming pleasant walks that teach you nothing.
Ask each shortlisted project for its complete schedule of charges in writing, and replace your estimates with those figures. If a loan will feature, seek an in-principle sanction now. Pre-approval tells you your real budget, surfaces documentation gaps while they are cheap to fix, and makes you a credible buyer to a seller who has heard promises before. Then recalibrate the target against the actual prices in front of you. A shortfall found at month nine is a schedule change. The same shortfall at month one is a crisis.
Saved is not the same as available
Money that is locked is not a down payment. Over the two quarters before your likely registration window, ladder your maturities so funds arrive slightly before they are needed. Nothing critical should mature after the window. Nothing large should sit in an instrument whose exit penalty you have not priced. Consolidate scattered balances; nobody has ever been helped at a counter by money in five places.
This is also the quarter to finish the legal work on the specific plot — the title chain and encumbrance searches described in our guide to verifying a land title. A funded buyer with an unverified parcel is no closer to ownership than an unfunded one, and is in more danger, because they can act.
The last ninety days run on bank cut-off times
Pay the token advance from the dedicated account, through banking channels, against a written agreement of sale that records the price, the plot, the timeline and what happens to the advance if either side walks. Cash advances protect nobody.
Then work backwards from the registration date. Confirm with the seller and your advocate exactly which instruments are required, in whose favour, and through which channel the stamp duty is to be paid. Arrange them several days early. Banks have cut-offs, sub-registrars have working hours, and demand drafts are not issued by sentiment. Keep the buffer liquid until after registration; certified copies and incidental charges arrive in exactly that fortnight.
Where the real numbers come from
Four sources, and none of them is a blog. Stamp duty and registration charges: IGRS Telangana, or the sub-registrar's office for the relevant village. The funded share, tenure and rate on a plot loan: the lender you will actually borrow from, in writing. Tax treatment of any of it: a chartered accountant who has seen your returns. Project charges: the developer's written schedule, signed.
Every figure in your plan should be traceable to one of those four. The ones that cannot be traced are the ones that move at the counter.
When the corridor moves while you are still saving
Two years of watching a belt means watching prices change, in one direction or the other. If prices in your target corridor firm faster than the corpus grows, the two bad responses are buying with a borrowed shortfall and abandoning the corridor for somewhere cheaper you have never researched. The measured responses are duller and better: raise the transfer, extend the timeline, take a smaller plot in the same verified layout, or accept a slightly longer commute along the same road.
If prices hold or soften, do not read the pause as a verdict. A corridor anchored by real infrastructure — a road that goes somewhere, a rail station, an institution — is judged over a holding period, not a quarter. The plan's advantage is that it turns market movement into a parameter you adjust rather than a drama you join. Plotted land rewards patient, lightly leveraged capital, and the plan exists to keep you in that category.
Money from family, employers and abroad
Family contributions are common and should be documented, either as a registered gift deed or as a clean banking trail from a close relative. The question "where did this money come from" is asked at inconvenient moments, and the answer should already be on paper.
Employer bonuses and vested stock go through the by-rule split you set at the beginning. For NRI buyers, the corpus generally accumulates abroad and remits through NRE or NRO accounts under FEMA, with residential plots permitted and agricultural land restricted. Spreading remittances over several months rather than converting in a single week reduces exposure to one day's rate and builds the trail your bank will want. Next Edge Realty handles FEMA-compliant purchases regularly; the discipline is identical in any currency.
Four ways the plan breaks
Borrowing the down payment. A personal loan stacked on a plot loan compounds unsheltered interest and tells every lender who looks that you are stretched.
Raiding the emergency fund. The fence around the fourth bucket is the plan.
Turning brave in the final year. Corpus moved into speculative positions near the finish line has cost buyers their registration date.
Dealing in cash. Every protection you have, from the agreement of sale to the deed itself, runs on traceable payment.
The funded buyer buys a different plot
Certainty is the one thing a seller cannot manufacture. A buyer with staged liquidity, a current sanction and the duty already provisioned can commit to a short registration timeline and mean it, and sellers concede more to that than to enthusiasm. The saving plan does not only decide whether you buy. It decides what you can hold out for.
None of this is financial advice. Rates, duties and tax treatments change, and your decisions belong with your own advisers; verification of title and approvals remains the buyer's responsibility, and property values are subject to market conditions. So do this in order. Get the written schedule of charges, get the duty figure from IGRS Telangana, get the funded share from your lender, and only then set the monthly transfer. When the arithmetic is done and the account is filling, book a site visit and walk the ground you are saving for.